Key points
- Track before you plan
- Pay yourself first
- Aim for sustainable, not perfect
- Review regularly
Building a budget that actually works: what to know
A budget is not a restriction — it is a plan that gives your money direction. Without one, money drifts: it arrives, it disappears, and you are left at month-end wondering where it went. With one, money becomes a tool that does what you intend it to do, and a surprising amount of anxiety simply falls away.
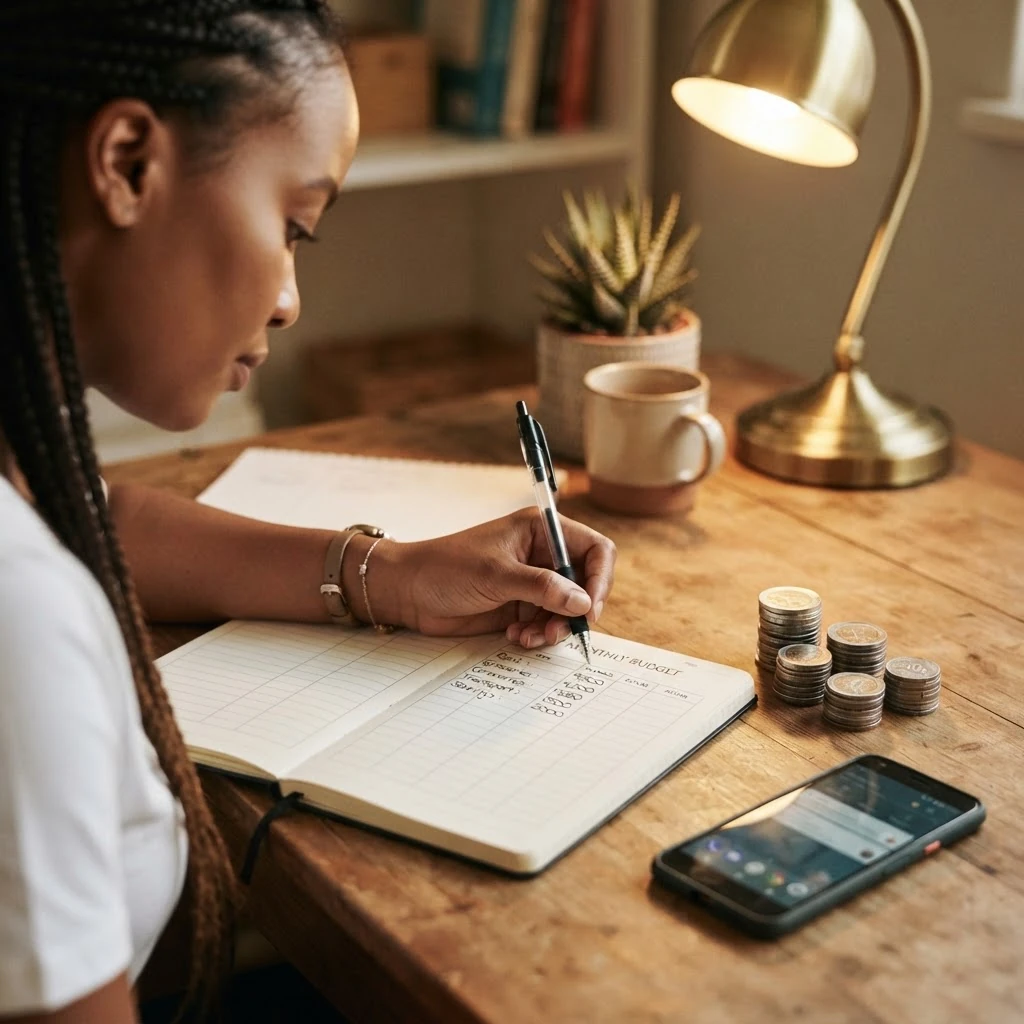
The most effective budgets start not with limits but with understanding. Before making any changes, track what you actually spend for a full month. Every coffee, every subscription, every debit order. The exercise is rarely encouraging, but it is always illuminating — and it replaces guesswork with facts, which is the only basis a durable budget can be built on.
From there, a simple framework helps. Allocate to essentials first (housing, food, transport, debt minimums), then to savings and debt reduction, then to discretionary spending. The order matters enormously; 'paying yourself first' — saving the moment income arrives, before anything else — is what ensures savings happen rather than hoping leftovers will appear. They rarely do.
A useful guideline, not a rule, is the 50/30/20 split: roughly half to needs, a portion to wants, and a portion to savings and debt. The exact numbers matter less than the habit of deliberately dividing money before it gets spent. Adjust the ratios to your reality; a family on a tight income will look very different to a single earner with surplus.
Aim for a budget you can sustain, not a perfect one. A strict budget abandoned in three weeks is worse than a loose one followed for three years. Consistency beats intensity in money, just as it does in fitness. If your plan requires heroic willpower every day, it will fail; if it makes room for the life you actually enjoy, it will last.
Build in a small 'no-questions-asked' discretionary amount. Guilt-free spending within a plan is what makes the plan survivable. A budget that allows for nothing enjoyable is one nobody keeps, and a budget you don't keep protects you from nothing.
Review your budget monthly at first, then quarterly as it stabilises. Adjust as your life changes — a new job, a move, a child, an interest-rate shift. A budget is a living document, not a stone tablet, and the act of revisiting it regularly is what keeps it accurate and useful for years.
This article provides general educational information. It does not replace advice from a qualified health professional.